
A year ago, Doric Weekly Insight opened on a note of euphoria, highlighting that the dry bulk sector had closed February at 2,111 points – a level last seen during this trading period in 2010. Twelve months later, the benchmark for dry bulk activity ended February at 1,229 points, having spent much of the first two trading months in three-digit territory. However, a direct comparison between the two years may not be entirely appropriate. Over the past fifteen trading years, the spot market has rarely recorded end-February levels above 1,000 points, let alone the 2,000-point threshold. In fact, excluding the COVID-19-disrupted 2022 and the front-loaded 2024, one must go back to 2010 to find a similarly strong market at this time of year.
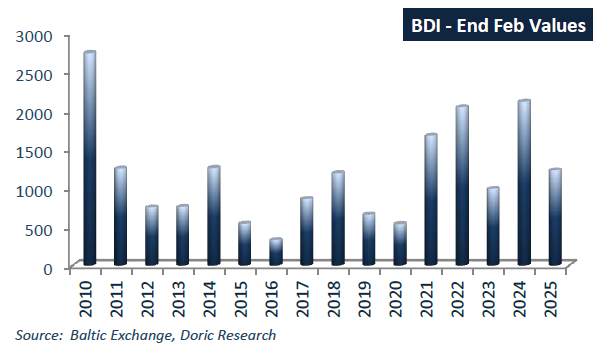
Against this backdrop, 2025 has been relatively lukewarm, yet the end-February level still stands above both the average and median values of the past fifteen years. By segment, Capesize led the market, closing at $15,074 per day – its highest level of the year and significantly above mid-February’s multi-month lows. The Panamax and Supramax markets, settling at $9,569 and $9,275 per day, respectively, remained below their recent peaks. Meanwhile, the Handysize segment erased all its 2025 losses by month-end, balancing at $9,844 per day.
On the macroeconomic front, India’s economic growth in the previous quarter fell short of market expectations but still expanded at a solid 6.2 percent, driven by increased government and consumer spending, according to data released on Friday. The Reserve Bank of India (RBI) had projected GDP growth of 6.8 percent, while both an Economic Times poll and a Reuters survey had forecast a 6.3 percent expansion for the third quarter. The latest reading also marked a slowdown from the 8.6 percent growth recorded in the same quarter of the previous financial year. Nevertheless, India remains the fastest-growing major economy in the world.
Government spending rose 8.3 percent in the last three months of 2024, a notable acceleration from the 3.8 percent increase in the preceding quarter. Private consumption, a key driver of the economy, jumped 6.9 percent year-on-year, up from 5.9 percent in the prior quarter, buoyed by improved rural demand amid moderating food prices and stronger festival-related spending. Exports also performed well, rising 10.4 percent in the third quarter of 2024–25, a sharp increase from the 3 percent growth seen a year earlier. Meanwhile, imports declined by 1.1 percent, slipping into negative territory – a trend partly attributed to the depreciation of the rupee.
India’s industrial output remained resilient, with the Index of Eight Core Industries (ICI) rising by 4.6 percent in January 2025 compared to the previous year, according to commerce ministry data released on Friday. Cement, refinery products, coal, steel, fertilizers, and electricity all recorded positive growth. The cumulative ICI growth rate for April 2024 to January 2025 stood at 4.4 percent on a provisional basis.
Steel production, in particular, saw robust expansion, rising significantly in January 2025 compared to the same month in 2024. The cumulative steel index increased by 5.9 percent year-on-year during the April-January period, making India the only major steel producer in the Pacific region to report growth in the first month of the year, according to the World Steel Association. India’s steel output reached 13.6 million tonnes in January, up 6.8 percent. In contrast, China’s production fell to 81.9 million tonnes, marking a 5.6 percent decline from January 2024. Japan and South Korea also reported contractions, with output dropping 6.6 percent and 8.8 percent, respectively. Overall, world crude steel production for the 69 countries reporting to the World Steel Association was 151.4 million tonnes in January, a 4.4 percent decrease compared to January 2024.
To further support economic growth, India’s central bank announced a rate cut earlier this month – the first in nearly five years. The Monetary Policy Committee signaled openness to further easing, with most members emphasizing the need to sustain growth. Against this backdrop, the government raised its full-year GDP growth forecast slightly on Friday, now expecting the economy to expand by 6.5 percent in the financial year ending March 31, up from its previous estimate of 6.4 percent.
Whether India alone can drive a broader market recovery remains debatable, but its sustained economic expansion, robust industrial production, and rising steel output provide crucial support to various segments of the dry bulk shipping market. With growing demand for raw materials, India continues to shape regional trade flows, reinforcing its role as a key driver of bulk carrier activity. However, the broader market landscape remains complex, with global macroeconomic uncertainties tempering sentiment. In this context, while February’s market levels may not compare to the euphoria of early 2024, they remain above historical averages, offering a degree of resilience. Ultimately, the trajectory of the market in the coming months will prove far more significant than the strength or weakness of its early-year performance, as the first quarter rarely sets the tone for the full year ahead.
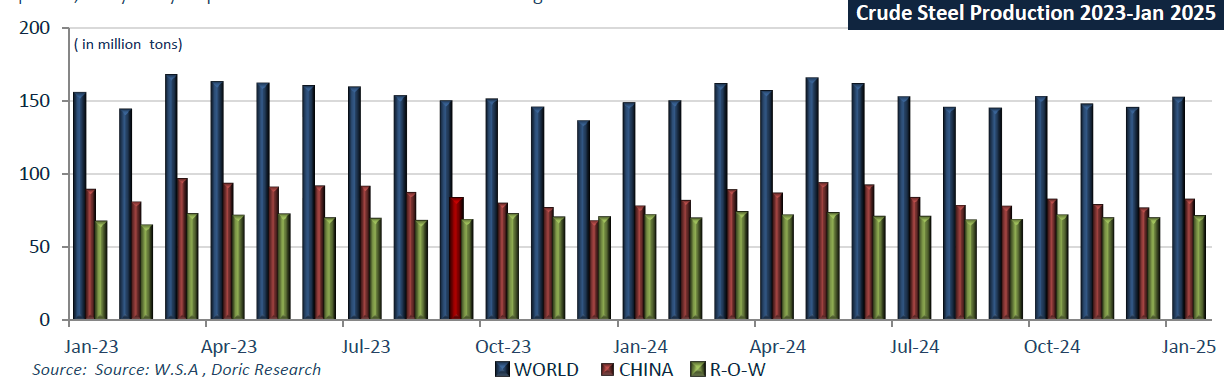
Data source: Doric