
By Ulf Bergman
Macro/Geopolitics
Much of today’s focus will be on the European Central Bank and its decision on interest rates due this afternoon. The bank look set to follow the US Federal Reserve’s example with a substantial move to combat surging price levels, with economists expecting interest rates to rise from zero to 0.75 per cent. The balancing act facing the bank’s policymakers of controlling the rising inflation without imposing too much economic pain on the continent has become somewhat less arduous following yesterday’s upward revision of the currency area’s GDP for the second quarter.
Local authorities in the Chinese city of Chengdu have extended the weeklong lockdown in most of the city’s central areas, while some outlying districts have seen restrictions eased. The move came as more cases of Covid infections were discovered during the mass testing of the city’s 21 million inhabitants, raising fears that a repeat of the disruptive lockdown that faced Shanghai earlier in the year may be on the cards.
Commodity Markets
Crude oil prices tumbled yesterday as a weakening demand outlook driven by aggressive monetary tightening and persistent economic concerns, partially fuelled by rising Covid infection rates, in the world’s preeminent importer, China, continued to weigh on the prices. The Brent futures dropped by 5.2 per cent and settled at 88 dollars per barrel, the lowest level since late January. The crude oil markets have continued lower in today's trading, after initially gaining some ground.
Despite the ongoing supply disruptions, the increasingly gloomy outlook for the global economy also weighed on the European natural gas market. Front-month futures registered a daily loss of nearly eleven per cent during a volatile session and settled at 213.88 euros per megawatt-hour. The decline has continued during today’s early trading, with the contracts approaching 200 euros.
The general malaise across the energy markets also affected thermal coal prices. The Newcastle futures for delivery in October shed 3.7 per cent and ended the day at 435 dollars per tonne, while the contracts for delivery in North-West Europe next month dropped by more than six per cent to 358 dollars per tonne.
Iron ore futures trading at the Singapore Exchange only saw marginal losses yesterday, with the October contracts retreating by just over half a per cent to 96.46 dollars per tonne. However, the market has seen a rebound today, with the futures advancing by around four per cent to breach 100 dollars per tonne.
The heavy mood across the commodities markets also affected the base metals, with most of them ending the day in the red. The copper futures trading at the London Metal Exchange retreated by 0.8 per cent for the day, while the aluminium and zinc contracts fell by more than one per cent. In contrast, the nickel futures ended the session unchanged.
The wheat futures trading in Chicago went against the flow yesterday. They gained 3.3 per cent following negative comments from the Russian president over the deal that has allowed Ukraine to resume its grains exports. The Russian leader suggested that a renegotiation of the terms may be required. In contrast, the soybean and corn futures retreated by around one per cent amid the weaker demand outlook.
Freight Markets
The markets for seaborne freight experienced a day of mixed performances yesterday. For the dry bulk sector, the 1.7 per cent gain for the headline Baltic Dry Index obscured the diverging fortunes across the different tonnage segments. The sub-index for the largest vessels, the Capesizes, continued to move lower following the recent brief recovery and retreated by 9.9 per cent. In contrast, the gauge for the Panamaxes soared by 11.6 per cent following robust ordering, especially for coal transports. The smaller vessels only registered minor changes to their freight rates, with the Baltic’s Supramax index declining by 0.3 per cent and the Handysize indicator gaining 0.2 per cent.
Among the Baltic’s wet indices, only the gauge for the dirty tankers declined. The darkening demand outlook for crude oil saw the index retreating by 1.3 per cent, mirroring developments in the crude oil market. In contrast, according to the Baltic Exchange, their clean siblings saw their freight rates advance by 2.1 per cent on average. While the gauge for the LNG freight rates remained unchanged, the LPG index rose by 2.5 per cent.
The View from the Shipfix Desk
While thermal coal prices have been caught up in the general retreat among energy commodities recently, prices remain only a few per cent below their recent all-time highs amid strong global demand and limited supply growth. Unless the global economy enters a deep recession with substantial demand destruction, prices and demand look set to remain high.
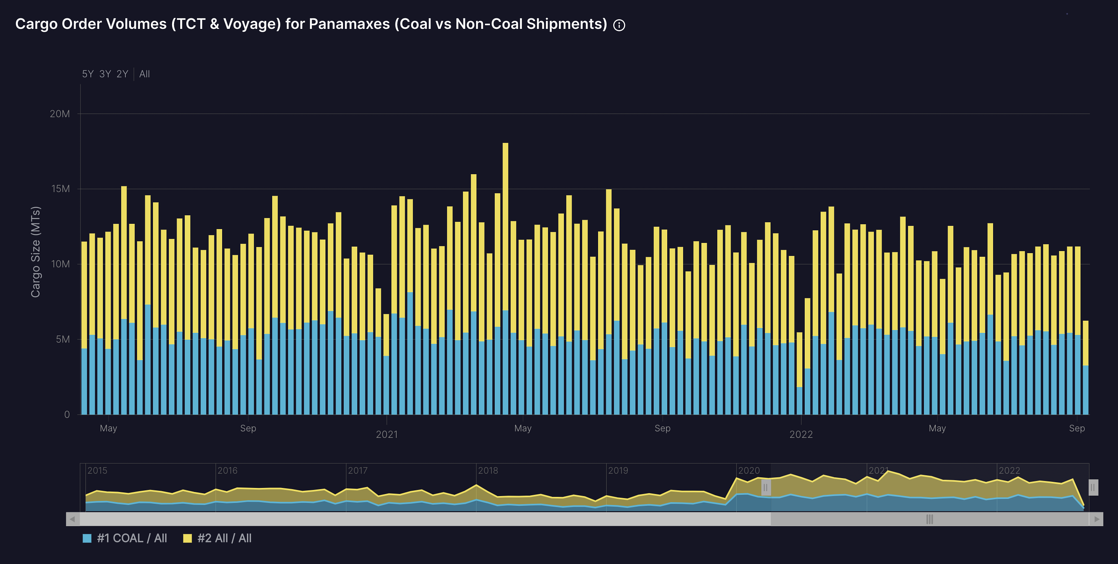
Freight rates for the Panamaxes have moved sharply higher in recent days, propelled higher by rising cargo order volumes. The Baltic Exchange’s index for the freight rates in the tonnage segment has gained nearly thirty per cent since the end of August. The continued robust demand for seaborne transportation of coal has been a significant contributor to the recovery in cargo order volumes. The current week is also on track to match recent strong weekly volumes. With winter approaching in the Northern Hemisphere, the development is also likely to continue as utilities rebuild their coal inventories.
Data Source: Shipfix